Medicare made clear · Statewide in Washington

Medicare in Washington State, explained by someone who actually teaches it.

Turning 65, retiring from Boeing or the state, or wondering whether your plan still includes your UW or Providence doctor? Sit down with a credentialed independent agent who will walk you through Medicare Advantage, Medigap and Part D in plain English — patiently, and at no cost to you.

No cost, no obligation, no pressure.

Request your free Medicare review

Tell us a little about you and Darin will reach out. Prefer to talk now? Call (702) 706-6564.

We never ask about your health on this form. See our Privacy Policy. This is a solicitation for insurance. Not connected with or endorsed by the U.S. government or the federal Medicare program.

Licensed in Washington · WA License #1010707 · NPN 18580338 Gerontologist & RSSA® 22-year U.S. Air Force veteran Always free to you

Washington is different

Three things about Medicare in Washington that the national websites gloss over

Washington has 39 counties, a mountain range down the middle that splits its health care in two, a state law on Medigap that most of the country would envy, and one of the largest military-retiree populations on the West Coast. Start with what actually applies where you live.

You can change Medigap plans any time

Washington law lets anyone who already holds a Medigap policy move to another Medigap plan at any point in the year, with no health questions. A Plan A holder can only move to another Plan A, and the rule is for existing Medigap policyholders, not for leaving an Advantage plan — but it changes how you shop, and how much a rate increase should worry you.

How the switching rule works

Two Washingtons, one mountain range

West of the Cascades the menu is deep and the question is which system your doctors belong to: UW Medicine, Providence Swedish, MultiCare, Virginia Mason Franciscan or Kaiser Permanente Washington. East of the passes, and along the coast, the menu is short and the nearest specialist may be two hours away, which is where a supplement’s any-provider access earns its premium.

What is really for sale in your county

A military state on Medicare

Joint Base Lewis-McChord, Naval Base Kitsap and Fairchild Air Force Base each anchor a large retiree community, and VA Puget Sound alone serves more than 125,000 veterans. TRICARE For Life and VA care each work with Medicare differently, and the Part B timing mistake is expensive and permanent.

Veterans & Medicare

Medicare in 2026, at a glance

The numbers that matter this year

Premiums and deductibles change every year. Here are the current 2026 Original Medicare figures — we refresh them annually so you are never reading last year’s numbers.

$202.90
Part B premium
Standard monthly, 2026
$283
Part B deductible
Annual, 2026
$1,736
Part A deductible
Per hospital benefit period, 2026
$2,100
Part D drug cap
Yearly out-of-pocket max, 2026

Source: Centers for Medicare & Medicaid Services, 2026 Medicare Parts A & B Premiums and Deductibles (released November 14, 2025) and 2026 Part D parameters. Higher earners may pay an income-related surcharge (IRMAA) — see our 2026 costs & IRMAA page.

Where to start

Four ways Washingtonians get covered

There is no single “best” plan — only the one that fits your doctors, your prescriptions, your county and your travel. Here is the plain-English version of your choices.

Medicare Advantage

All-in-one Part C plans, often $0 premium, that use a local network — so whether UW Medicine, Providence, MultiCare or Kaiser is in it matters as much as the price.

How Advantage works

Medicare Supplement

Medigap pairs with Original Medicare and lets you see any provider in the country that accepts Medicare — and in Washington you can change plans any time.

How Medigap works

Part D drug plans

Standalone drug coverage chosen around your medications and pharmacy. 2026 out-of-pocket cap: $2,100.

How Part D works

Special Needs Plans

Advantage plans built for a chronic condition, for nursing-facility care, or for people with both Medicare and Apple Health.

About SNPs

Your situation matters

Help for specific circumstances

The rules change a lot depending on what else you have and where in the state you live. These are the situations Washingtonians ask us about most.

Switching Medigap plans

Your premium went up, or you want Plan G instead of Plan F. Washington lets existing Medigap policyholders change plans year-round without underwriting. Here is exactly what the rule does and does not do.

Use the Washington rule

Which system is in my network?

UW Medicine, Providence Swedish, MultiCare, Virginia Mason Franciscan, Kaiser, Confluence, Kadlec — each contracts with some Advantage plans and not others, and the list changes every fall.

Check before you enroll

Veterans & military retirees

TRICARE For Life, VA Puget Sound, Mann-Grandstaff, Walla Walla — and why Part B timing still matters even with VA care.

Veterans & Medicare

Medicare + Apple Health

The Medicare Savings Programs that pay your Part B premium (income limits only, no asset test for 2026), Extra Help, and Dual Special Needs Plans that coordinate both.

Dual-eligible help

Free guide

New to Medicare? Start with Turning 65 in Washington.

A clear, step-by-step walk-through of your enrollment windows, the Washington-specific choices in front of you, and the deadlines that carry a lifelong penalty if you miss them. No sign-up required.

Read the Turning 65 guide Get the free 295-page book

Who you’ll be working with

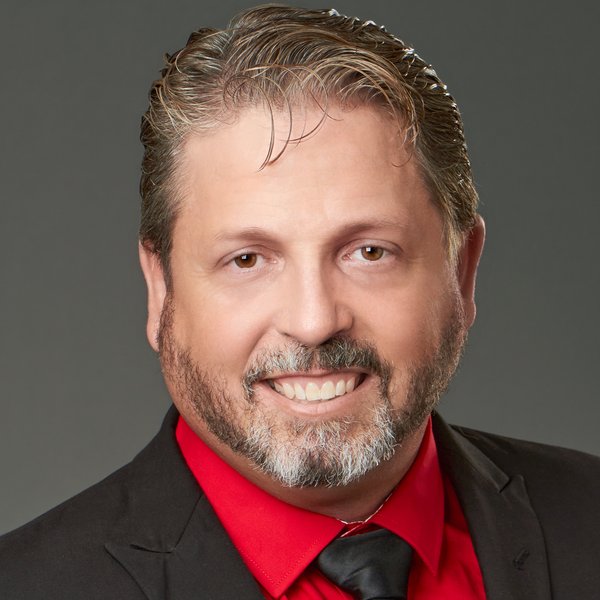
Darin Weidauer, independent Medicare insurance agent and credentialed gerontologist

Darin Weidauer, MBA, RSSA®

Gerontologist · Registered Social Security Analyst® · U.S. Air Force Veteran

  • NPN 18580338 · licensed in Washington, WA License #1010707
  • Credentialed gerontologist (2014)
  • RSSA®
  • 22-yr USAF veteran (retired officer)
  • Author, Retire With Confidence

Darin Weidauer (WA License #1010707) is an independent Medicare insurance agent, credentialed gerontologist, and Registered Social Security Analyst® who helps Washington State retirees and people approaching 65 make sense of their options — clearly, patiently, and with no cost to them. A 22-year U.S. Air Force veteran who retired as an officer, Darin holds five master’s degrees, including an MBA and a Master’s in Dispute Resolution from Pepperdine and a Master’s in Long-Term Care from USC, and became a credentialed gerontologist in 2014 — studying the human side of aging, not just the paperwork.

A former Professor of Aerospace Studies at Loyola Marymount University who has lectured at more than 50 colleges and universities, Darin now channels that teaching instinct into plain-English Medicare education through one-on-one reviews, no-cost workshops, and his book Retire With Confidence. More about Darin →
Questions Washingtonians ask

Frequently asked questions

How much does it cost to work with ECOS Medicare Solutions?

There is no cost to you. Independent Medicare agents are paid by the insurance carriers when you enroll, so our help comparing plans, answering questions, and reviewing your coverage each year is free. Your plan premium is the same whether you enroll with our help or on your own.

Can I really change my Medigap plan any time in Washington?

If you already have a Medigap policy, yes. Washington law lets you switch to another Medigap plan at any time of year without medical underwriting; the one limit is that a Plan A holder can only move to another Plan A. It does not apply to a move from Medicare Advantage into Medigap, which relies on your six-month open enrollment, a federal guaranteed-issue right, or underwriting. Our switching guide walks through it.

When can I enroll in or change my Medicare plan in Washington?

Most people first enroll during their Initial Enrollment Period, the seven months around their 65th birthday. After that, the Annual Election Period runs October 15 to December 7 each year, and the Medicare Advantage Open Enrollment Period runs January 1 to March 31. Moving counties, losing a plan, or qualifying for Apple Health opens a Special Enrollment Period, and Medigap policyholders can change plans any time.

Is UW Medicine in my Medicare Advantage plan?

It depends on the plan and the year. UW Medicine accepts Original Medicare, and therefore any Medigap policy. For 2026 it has said it will not be contracted with Humana, PacificSource or Wellpoint plans, and its list of contracted plans changes each fall. If UW Medicine, Fred Hutch, Providence Swedish, Virginia Mason or a specific system is your care, we confirm the plan’s status in writing before you enroll.

I have VA or TRICARE benefits. Do I still need Medicare?

Often, yes. VA health care and Medicare do not coordinate with each other, and TRICARE For Life requires you to have Medicare Parts A and B. Enrolling in Part B on time matters even with VA care, because VA medical coverage is not creditable for Part B and the late penalty lasts for life. Our Veterans page explains how these benefits fit together.

Do you offer every Medicare plan available in my area?

No — and we will always be upfront about that. We represent a number of insurance organizations and products in Washington, not all of them. The easiest next step is to call us at (702) 706-6564 and we will walk through what fits you. To compare every option on your own, Medicare.gov, 1-800-MEDICARE, and Washington SHIBA (800-562-6900) have the complete list.

Ready when you are

Let’s find the plan that fits your life.

A short, friendly conversation — no pressure, no cost. We’ll look at your doctors, your prescriptions, your county and your travel together.