Medicare made clear · Statewide in Florida

Medicare in Florida, explained by someone who actually teaches it.

Turning 65, just moved here, or re-shopping because your plan dropped your doctor? Sit down with a credentialed independent agent who will walk you through Medicare Advantage, Medigap and Part D in plain English — patiently, and at no cost to you.

No cost, no obligation, no pressure.

Request your free Medicare review

Tell us a little about you and Ronilin will reach out. Prefer to talk now? Call (702) 706-6564.

We never ask about your health on this form. See our Privacy Policy. This is a solicitation for insurance. Not connected with or endorsed by the U.S. government or the federal Medicare program.

Ronilin Weidauer, licensed in Florida · FL License #W690636 · NPN 19427652 Gerontologist & RSSA® 22-year U.S. Air Force veteran Always free to you

Florida is different

Three things about Medicare in Florida that the national websites gloss over

Florida has more people on Medicare Advantage than any state but California, more new retirees arriving every year than anywhere, and Medigap rules that reward buying early. Start with what actually shapes the choice here.

The Advantage market moved under your feet

AvMed left for 2026, UnitedHealthcare cut plans across South Florida, Tampa Bay and the Gulf Coast, and extras were trimmed almost everywhere. A discontinued plan opens a Special Enrollment Period and, usually, a guaranteed-issue right to Medigap.

What changed, and what to do

Medigap is issue-age rated here

Florida requires issue-age pricing: your premium cannot rise because you got older, only with the carrier’s filed increases. It rewards buying at 65 and punishes waiting. Florida also guarantees a Medigap window to people under 65.

Why the age you buy matters

You brought your Medicare with you

Moving from New York, Ohio or Minnesota changes your county, your plan menu, and sometimes your Medigap rights. The move itself opens a Special Enrollment Period; use it well.

Medicare for new Floridians

Medicare in 2026, at a glance

The numbers that matter this year

Premiums and deductibles change every year. Here are the current 2026 Original Medicare figures — we refresh them annually so you are never reading last year’s numbers.

$202.90
Part B premium
Standard monthly, 2026
$283
Part B deductible
Annual, 2026
$1,736
Part A deductible
Per hospital benefit period, 2026
$2,100
Part D drug cap
Yearly out-of-pocket max, 2026

Source: Centers for Medicare & Medicaid Services, 2026 Medicare Parts A & B Premiums and Deductibles (released November 14, 2025) and 2026 Part D parameters. Higher earners may pay an income-related surcharge (IRMAA) — see our 2026 costs & IRMAA page.

Where to start

Four ways Floridians get covered

There is no single “best” plan — only the one that fits your doctors, your prescriptions, your county and your travel. Here is the plain-English version of your choices.

Medicare Advantage

All-in-one Part C plans, often $0 premium, that use a county network — the dominant choice in Florida, and the one that changed most for 2026.

How Advantage works

Medicare Supplement

Medigap pairs with Original Medicare and works with any provider nationwide — Mayo Jacksonville, Moffitt, Cleveland Clinic, or your doctor back in Ohio.

How Medigap works

Part D drug plans

Standalone drug coverage chosen around your medications and pharmacy. 2026 out-of-pocket cap: $2,100.

How Part D works

Special Needs Plans

Advantage plans built for a chronic condition, for nursing-facility care, or for people with both Medicare and Florida Medicaid.

About SNPs

Your situation matters

Help for specific circumstances

The rules change a lot depending on what else you have and where you spend the year. These are the situations Floridians ask us about most.

New to Florida & snowbirds

What a move does to your plan, which plans work when you split the year, and why your Medigap rights may differ from up north.

Moving to Florida on Medicare

Hurricanes & Medicare

What a FEMA disaster declaration does to your enrollment deadlines, and how to keep prescriptions filled when you evacuate.

Hurricanes & Medicare

Veterans & military retirees

TRICARE For Life, the VA (Miami, Tampa, Bay Pines, Orlando, Gainesville, West Palm), and why Part B timing still matters.

Veterans & Medicare

Medicare + Florida Medicaid

The Medicare Savings Programs that pay your Part B premium, Extra Help, SMMC long-term care, and the D-SNPs that coordinate both.

Dual-eligible help

Free guide

New to Medicare? Start with Turning 65 in Florida.

A clear, step-by-step walk-through of your enrollment windows, the Florida-specific choices in front of you, and the deadlines that carry a lifelong penalty if you miss them. No sign-up required.

Read the Turning 65 guide Get the free 295-page book

Who you’ll be working with

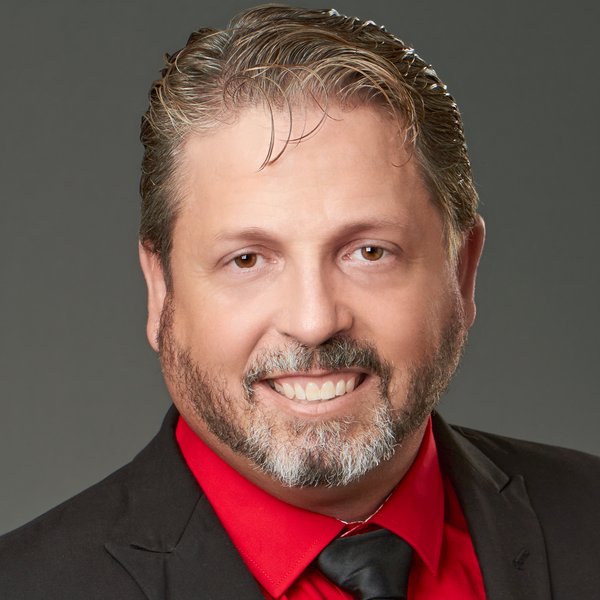
Darin Weidauer, independent Medicare insurance agent and credentialed gerontologist

Darin Weidauer, MBA, RSSA®

Gerontologist · Registered Social Security Analyst® · U.S. Air Force Veteran

  • Founder, ECOS Medicare Solutions · NPN 18580338
  • Your licensed Florida agent: Ronilin Weidauer · NPN 19427652, FL License #W690636
  • Credentialed gerontologist (2014)
  • RSSA®
  • 22-yr USAF veteran (retired officer)
  • Author, Retire With Confidence

Ronilin Weidauer is the licensed Florida insurance agent for ECOS Medicare Solutions (NPN 19427652, FL License #W690636) and the person who will take your call and walk you through your options. Darin Weidauer, the agency’s founder, is a credentialed gerontologist and Registered Social Security Analyst® who writes the pages on this site to help Florida retirees, new residents and people approaching 65 make sense of their options — clearly, patiently, and with no cost to them. A 22-year U.S. Air Force veteran who retired as an officer, Darin holds five master’s degrees, including an MBA and a Master’s in Dispute Resolution from Pepperdine and a Master’s in Long-Term Care from USC, and became a credentialed gerontologist in 2014 — studying the human side of aging, not just the paperwork.

A former Professor of Aerospace Studies at Loyola Marymount University who has lectured at more than 50 colleges and universities, Darin now channels that teaching instinct into plain-English Medicare education through one-on-one reviews, no-cost workshops, and his book Retire With Confidence. More about Darin →
Questions Floridians ask

Frequently asked questions

How much does it cost to work with ECOS Medicare Solutions?

There is no cost to you. Independent Medicare agents are paid by the insurance carriers when you enroll, so our help comparing plans, answering questions, and reviewing your coverage each year is free. Your plan premium is the same whether you enroll with our help or on your own.

My Florida Medicare Advantage plan was discontinued or dropped my doctor. What now?

You are not alone: AvMed left the Florida Medicare market for 2026 and UnitedHealthcare cut plans in many counties. A non-renewal notice gives you a Special Enrollment Period and, in most cases, a guaranteed-issue right to buy a Medigap policy without health questions, generally within 63 days of the coverage ending. A dropped doctor mid-year is harder; call us and we will check whether a Special Enrollment Period applies.

Why are Medigap premiums so high in Florida, and what is issue-age rating?

Florida requires issue-age rating: your premium is set by the age at which you buy and cannot rise because you got older, only with the carrier’s filed increases. Insurers price that promise in, and Florida’s claims costs are high, so premiums run above most states. The rule rewards buying at 65 and holding the policy.

I just moved to Florida. Do I have to change my Medicare plan?

Medicare Advantage, Part D and most Medigap decisions are tied to your county of residence. Moving to Florida gives you a Special Enrollment Period to pick plans sold here; a Medigap policy from another state usually stays in force but may be re-rated. If you came from a state with continuous Medigap guaranteed issue, such as New York or Connecticut, your rights here are different. Our new-to-Florida guide walks through it.

I have VA or TRICARE benefits. Do I still need Medicare?

Often, yes. VA health care and Medicare do not coordinate with each other, and TRICARE For Life requires you to have Medicare Parts A and B. Enrolling in Part B on time matters even with VA care, because VA medical coverage is not creditable for Part B and the late penalty lasts for life. Our Veterans page explains how these benefits fit together.

Do you offer every Medicare plan available in my area?

No — and we will always be upfront about that. We represent a number of insurance organizations and products in Florida, not all of them. The easiest next step is to call us at (702) 706-6564 and we will walk through what fits you. To compare every option on your own, Medicare.gov, 1-800-MEDICARE, and SHINE (1-800-963-5337) have the complete list.

Ready when you are

Let’s find the plan that fits your life.

A short, friendly conversation — no pressure, no cost. We’ll look at your doctors, your prescriptions, your county and your calendar together.